How Compound Interest works?

 
Personal Finance article in Advisorkhoj - How Compound interest works

Compound interest is the eighth wonder of the world. He who understands it, earns it... he who doesn't... pays it. - Albert Einstein

In our previous article we discussed the benefits of start investing early for wealth creation and we also discussed how it is possible using 'power of compounding'. Now, let's understand how Compound Interest works in your favour?

Compound interest is the concept of adding earned or accumulated interest back to the principal amount, so that interest is earned on top of interest from that period onwards. The act of adding declared interest to be principal is called compounding.

It is similar to simple interest (in simple interest, the interest portion in not added to the principal) but, here the interest will be added to the principal after a certain unit of time (e.g. Monthly, Quarterly, Half – yearly and Annually etc.). Example – a savings of Rs.10,000 at 10% annual interest will become 11,000 after 12 months. Here, the interest amount is Rs.1,000. But, the interest amount after 24 months would be Rs.1,100 as at the end of 24 month the Interest is calculated on Rs.11,000 (i.e. Rs.10,000 + Rs. 1,000 – Interest earned in the 1st Year)! This is possible as the interest will be paid both on the principal and on the interest that has been added to it. In other words, we can say, interest itself earns interest!

The compounding period and the frequency of compounding apart from the interest rate are the major components of compound interest calculation. The frequency (Annual, Half-year, Quarter or month) after which an interest earned during that period added to the principal is called as compounding period. Now, let's understand these with formulas on different compound periods.

When the interest is compounded annually then the following formula will be used to calculate the yearly compounding interest –
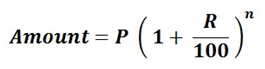
Personal Finance - Yearly compounding interest formula

When the interest is compounded half - yearly then the following formula will be used to calculate the half-yearly compounding interest –
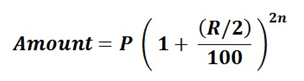
Personal Finance - Half-yearly compounding interest formula

When the interest is compounded quarterly then the following formula will be used to calculate the Quarterly compounding interest –
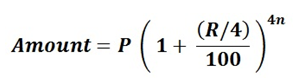
Personal Finance - Quarterly compounding interest formula

When the interest is compounded monthly then the following formula will be used to calculate the monthly compounding interest –
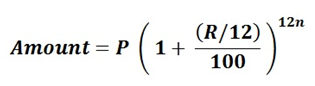
Personal Finance - Monthly compounding interest formula

In the above formula the P denotes the Principal amount. R denotes the percentage of interest and n denotes the time in years or months (n means annual, 2n means half-year, 4n means quarter and 12n means monthly).

Now, let's understand 'how to calculate and get the results in excel'? The following shows the result of Rs.10,000 invested at 10% interest for 5 years at different compounding periods.

Result of annual compounding
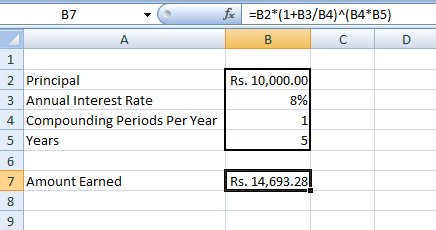
Personal Finance - Result of annual compounding

Result of half-yearly compounding
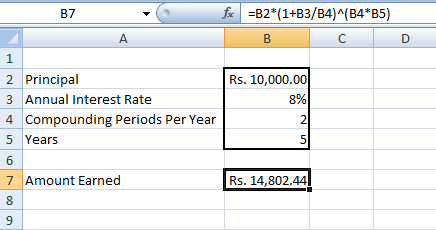
Personal Finance - Result of half-yearly compounding

Result of quarterly compounding
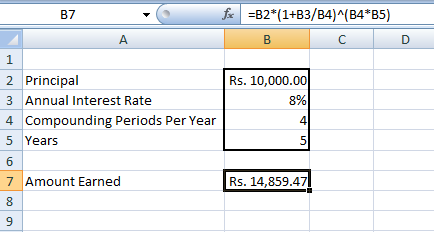
Personal Finance - Result of quarterly compounding

Result of monthly compounding
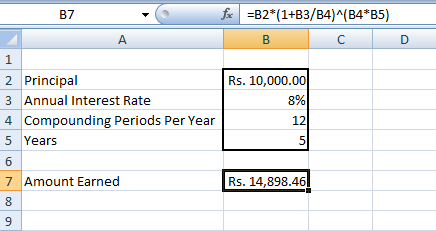
Personal Finance - Result of monthly compounding

Hope, you find that above useful.

-----------------------------------------------
Invest Rs 1,50,000 and Save Tax under Section 80C. Get Great Returns by Investing in Best Performing ELSS Mutual Funds

Top 10 Tax Saving Mutual Funds to invest in India for 2016

Best 10 ELSS Mutual Funds in india for 2016

1. BNP Paribas Long Term Equity Fund

2. Axis Tax Saver Fund

3. Franklin India TaxShield

4. ICICI Prudential Long Term Equity Fund

5. IDFC Tax Advantage (ELSS) Fund

6. Birla Sun Life Tax Relief 96

7. DSP BlackRock Tax Saver Fund

8. Reliance Tax Saver (ELSS) Fund

9. Religare Tax Plan

10. Birla Sun Life Tax Plan

Invest in Best Performing 2016 Tax Saver Mutual Funds Online

Invest Online

Download Application Forms

For further information contact Prajna Capital on 94 8300 8300 by leaving a missed call

---------------------------------------------

Leave your comment with mail ID and we will answer them

OR

You can write to us at

PrajnaCapital [at] Gmail [dot] Com

OR

Leave a missed Call on 94 8300 8300

-----------------------------------------------

Popular posts from this blog

Atal Pension Yojana contribution Tax Benefit for spouse

Contributions to Atal Pension Yojana (APY) are eligible for the same tax benefits as the NPS. This means that the contributions can be claimed under Section 80CCD (1B). The current limit for Section 80CCD (1B) is   Rs   50,000, over and above the   Rs   1.5 lakh limit under Section 80C. Section 80 CCD (1) is a different one, meant to cover employers' contribution towards NPS . You cannot get tax benefit by investing in the name of your spouse under Section 80 CCD . ------------------------------ ----------------- Invest Rs 1,50,000 and Save Tax under Section 80C. Get Great Returns by Investing in Best Performing ELSS Mutual Funds Top 10 Tax Saver Mutual Funds to invest in India for 2016 Best 10 ELSS Mutual Funds in India for 2016 1. BNP Paribas Long Term Equity Fund 2. Axis Tax Saver Fund 3. Religare Tax Plan 4. DSP BlackRock Tax Saver Fund 5. Franklin India TaxShield 6. ICICI Prudential Long Term Equity Fund 7. IDFC Tax Advantage (ELSS) Fund 8. Birla Sun Life Tax Relief 96 9. ...

Franklin India High Growth Companies Fund

Franklin India High Growth Companies Fund Online One of the key developments that the Street is keenly waiting for is a cut in interest rates by Reserve Bank of India . With demand rising gradually, a rate cut is expected to boost earnings growth for companies. In such a situation, schemes which invest in high growth companies are best suited, especially when seen from a long-term perspective. One such scheme is Franklin India High Growth Companies Fund. Fund managers Anand Radhakrishnan, Roshi Jain and Srikesh Nair strictly follow valuation parameters when it comes to choosing stocks.Valuation parameters, such as enterprise value, price-to-earnings growth ratio, forward price-to-sales ratio and discounted earnings per share, play a critical role in selecting companies for investments. Taking into account these parameters, the fund managers invest in companies which are poised for high growth in their respective sectors. This approach has been in favour of the scheme and it has perform...

Avoid NFOs

  Don't get taken in by the flurry of new fund offers. You will be better off sticking to the tried and tested schemes.   For the past one year, to cash in on the bull run in equities, mutual fund houses have gone on a new fund offer (NFO) overdrive. But experts are unanimous in their advice: avoid NFOs . While past performance is not an indicator of how a fund will fare in the future, it does tell the investor how skilful the fund manager is. This crucial information is missing in an NFO. Not only is there no track record to judge an NFO by, many NFOs are similar to funds that already exist. If the new fund is similar to existing funds, you are better off investing in the latter. Around 67% of the new launches in 2014 were closed-end products. Investing in the NFO of a closed-end fund is doubly risky. In case the fund's performance is lacklustre, a closed-end fund does not allow you to exit. Even though closed-end funds are listed on the stock...

Debt Mutual Fund Dividends are Taxable

DDT is deducted when a non-equity fund declares dividends. Equity and balanced fund dividends are tax-free The AMC is correct to deduct the dividend distribution tax (DDT) as it is mandated by tax laws. DDT in mutual funds is deducted every time a non-equity fund declares dividends. Equity fund and balanced fund dividends are tax-free . It is possible that you have invested in a non-equity fund for the first time or have received the dividend under a non-equity fund for the first time. That is why this is the first occasion when you have come across DDT.   The rate at which non-equity schemes deduct DDT has also gone up after the July 2014 budget. This is due to a change in calculation methodology. Earlier, if the fund has to declare a dividend of R 100, it used to make a provision for R 128.3, paying R 28.3 to the taxman and distributing the balance to the investor. This allowed the investor to bear less tax since the effective tax rate was 22.07 per ce...

RBI frees savings rates in cooperative banks

Tax Saving Mutual Funds Online Current open Infra Bond Application form The central bank had deregulated rates for commercial banks in October THE Reserve Bank of India (RBI) on Monday deregulated interest rate on savings accounts in all state and central cooperative banks, a move that will fetch better returns for depositors. RBI had freed these rates for the scheduled commercial banks in October. In a notification addressed to all state and central cooperative banks, RBI said they are free to determine their savings bank deposit interest rate subject to two conditions. Under the first condition, the notification said, "Each bank will have to offer a uniform interest rate on savings bank deposits up to Rs 1,00,000, irrespective of the amount in the account within this limit." The other condition states that for savings bank deposits over Rs 1,00,000, a bank may provide differential rates of interest, if it so chooses. This would, howev er, be subje...
Related Posts Plugin for WordPress, Blogger...
Invest in Tax Saving Mutual Funds Download Any Applications
Transact Mutual Funds Online Invest Online
Buy Gold Mutual Funds Invest Now