
Joint Life Term Insurance Policies


We all know there are term plans available in the market for individuals. But when both husband and wife are earning then why to buy separate term insurance and why not buy a Joint Life Term Insurance? Currently, few insurance companies started to offer such plans. Let us see the details of such plans.

In this plan, both husband and wife will be proposer. Hence, a spouse must undergo the medical test and produce the income proof. Along with these mandatory requirements, both husband and wife must submit all other necessary documents.

Currently in the market, there are so many variants of joint life term insurance policies. However, the two main types are as below.

  • Insurance companies pay the death claim amount in the event of any one's death (husband or wife). The policy stops there itself (Also called Single Payout policies). Usually such types of joint life term insurance are cheap.
  • Insurance companies pay the death claim amount in the event of any one's death (husband or wife). The surviving spouse will be covered for the sum assured as usual (few may offer premium waiver benefits).

Now let us consider the situations, where spouse bought Rs.1 Cr Joint Life Term Insurance. How the claim be settled in different situations. I considered the basic feature of Joint Life Term Insurance.

Case 1-Joint Life Term Insurance Policy-1
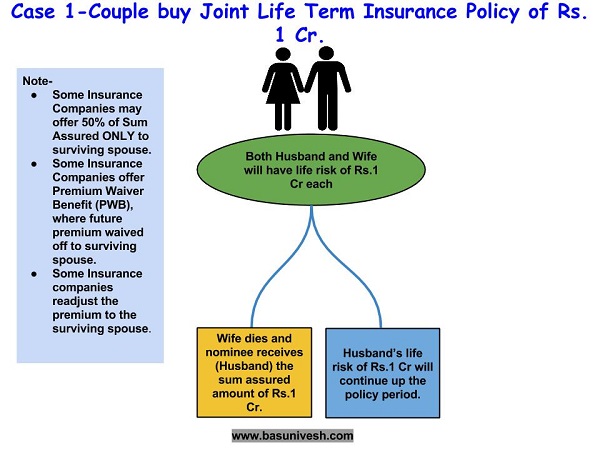
In this case, either a wife or husband dies and the sum insured will be payable to the nominee (husband). The future premium will be waived off. Surviving spouse's life risk will continue as usual up to the remaining policy period. However, as I mentioned in the above note, few companies may offer 50% of the sum assured to the surviving spouse. Another point to note is, few companies have the inbuilt premium waiver benefit, but some may offer it as an additional rider (for which you have to pay the extra premium). Finally, few companies either continue the same premium rate for a surviving spouse or reduce it as the number of insured will come down.

What I explained above is a simple example of the joint life term insurance. However, check with individual insurance companies before going for such joint life term insurance products.

Case 2-Joint Life Term Insurance Policy-2

In the above case, death of a spouse occurs together. In such situation, nominee will receive the sum assured amount. Policy terminates there itself.


Case 3-Joint Life Term Insurance Policy-3
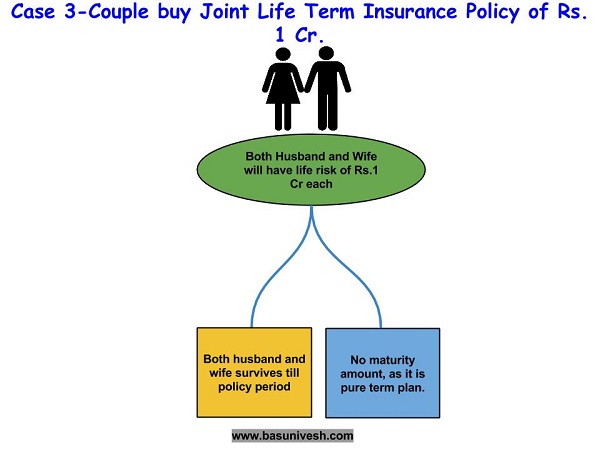
In this case, both husband and wife survive until policy period. As this is pure term plan, both will not get any maturity benefit and policy closes at the maturity date.

Advantages of Joint Life Term Insurance-

  • Ease of manage-By holding a single policy, it is easy for a couple to manage their life insurance need.
  • Premium Benefit-Instead of buying an individual policy, if you go with a joint life term insurance policy, then the premium will get reduced.
  • Some joint life term insurance policies consider the average age of spouse, which may be beneficial in terms of premium rate consideration. However, do remember that some insurance companies may consider the age of the spouse who is older (like family floater health insurance policies).

Disadvantages of Joint Life Term Insurance–

  • In the name of joint Life Insurance, your agent may sell you joint life ENDOWMENT PLAN. Hence, be cautious while buying.
  • In case spouse death occurs together, then nominee receive on the sum assured. However, if spouse buys separate term insurance, then death claim amount will be based on individual policies sum assured.
  • In case of single payout policies, the surviving spouse has to continue without any life insurance.
  • If wife stayed away from the job due to managing kids, then no insurance required for her. However, buying such joint life insurance may hard to discontinue, in such situation or separate insured.
  • In case of divorce, it is hard to delete any one insured and continue the policy. Either you have to continue the policy in joint name or discontinue.

Which companies currently offer such joint life term insurance products?

Currently, few companies offer such policies with a variety of features. Some of them are as below.

  • PNB MetLife's Mera Term Plan
  • Aegon Religare's iSpouse
  • Bajaj Allianz iSecure

Note-As I said above, there is no uniformity of features among all joint life term insurance policies. Hence, check for features carefully before jumping into it.

-----------------------------------------------
Invest Rs 1,50,000 and Save Tax under Section 80C. Get Great Returns by Investing in Best Performing ELSS Mutual Funds

Top 10 Tax Saving Mutual Funds to invest in India for 2016

Best 10 ELSS Mutual Funds in india for 2016

1. BNP Paribas Long Term Equity Fund

2. Axis Tax Saver Fund

3. Franklin India TaxShield

4. ICICI Prudential Long Term Equity Fund

5. IDFC Tax Advantage (ELSS) Fund

6. Birla Sun Life Tax Relief 96

7. DSP BlackRock Tax Saver Fund

8. Reliance Tax Saver (ELSS) Fund

9. Religare Tax Plan

10. Birla Sun Life Tax Plan

Invest in Best Performing 2016 Tax Saver Mutual Funds Online

Invest Online

Download Application Forms

For further information contact Prajna Capital on 94 8300 8300 by leaving a missed call

---------------------------------------------

Leave your comment with mail ID and we will answer them

OR

You can write to us at

PrajnaCapital [at] Gmail [dot] Com

OR

Leave a missed Call on 94 8300 8300

-----------------------------------------------

Popular posts from this blog

Mutual Fund Exit Load Changes

Download Tax Saving Mutual Fund Application Forms Invest In Tax Saving Mutual Funds Online Buy Gold Mutual Funds Leave a missed Call on 94 8300 8300 Mutual Fund Exit Load Changes AMCs don't communicate about any change in exit load directly with investors, but do update on their website   The exit load applicable to your investments is the load which existed at the time when you invested in the particular fund. Any subsequent changes in the exit load will not be applicable to your investments.   However, Asset Management Companies ( AMCs ) periodically publish addendums in the newspapers, which state any change in exit loads of specific schemes managed by them. Such changes are also posted on their websites. However, a direct communication to an investor is not made, considering the costs involved in doing so. In their own interests, investors should not only track the performance of the funds they i...

Atal Pension Yojana contribution Tax Benefit for spouse

Contributions to Atal Pension Yojana (APY) are eligible for the same tax benefits as the NPS. This means that the contributions can be claimed under Section 80CCD (1B). The current limit for Section 80CCD (1B) is   Rs   50,000, over and above the   Rs   1.5 lakh limit under Section 80C. Section 80 CCD (1) is a different one, meant to cover employers' contribution towards NPS . You cannot get tax benefit by investing in the name of your spouse under Section 80 CCD . ------------------------------ ----------------- Invest Rs 1,50,000 and Save Tax under Section 80C. Get Great Returns by Investing in Best Performing ELSS Mutual Funds Top 10 Tax Saver Mutual Funds to invest in India for 2016 Best 10 ELSS Mutual Funds in India for 2016 1. BNP Paribas Long Term Equity Fund 2. Axis Tax Saver Fund 3. Religare Tax Plan 4. DSP BlackRock Tax Saver Fund 5. Franklin India TaxShield 6. ICICI Prudential Long Term Equity Fund 7. IDFC Tax Advantage (ELSS) Fund 8. Birla Sun Life Tax Relief 96 9. ...

Birla Sun Life Mutual Fund Launches Birla Sun Life NIFTY ETF

Birla Sun Life has launched a new fund namely, Birla Sun Life Nifty ETF, an open ended exchange traded fund. The new fund will be open for subscription from 4th July to 18th July 2011, at an offer price of Rs 10 per unit. The investment objective of the scheme is to generate returns that closely correspond to the total returns of securities as represented by S&P CNX Nifty, subject to tracking errors. No exit load will be charged under the scheme. The performance of the scheme will be benchmarked against S&P CNX Nifty and will be managed by Satyabrata Mohanty.   -----------------------------------------------------------------   Also, know how to buy mutual funds online:   1) DSP BlackRock Mutual Funds: http://prajnacapital.blogspot.com/2011/05/buying-dsp-blackrock-mutual-funds.html   2) Reliance Mutual Funds: http://prajnacapital.blogspot.com/2011/06/buying-reliance-mutual-funds-online.html   3) Birla Sunlife Mutual Funds: http://prajnacapital.blogspot.com/2011/...

Mutual Fund Reivew: Birla Sun Life Asset Allocation Conservative

Birla Sun Life Asset Allocation Conservative has numbers on its side to prove its credibility… Don't be surprised to find this Fund of Funds ( FoF ) in our recommendations. It has earned its place. And despite the difference in the structure of the product, there is no arguing with the numbers.   Of the total 6 years of its existence, the fund has been among the top 10 funds in its category in four of them. Last year it put up an average show and the only year it underperformed its peers was in 2008.   One aspect to look at when investing in an FoF is the expense ratio. The expense ratio of an FoF is capped at a lower limit of 0.75 per cent (2.50% for an actively managed fund). However, the FoF not only has its own expense (though lower) but even the expense ratio of the fund it is investing into. Fortunately, the fund manager takes that into account. "Expense is one of the important criteria used for fund selection and is the main reason for our investment in BSL Ind...

Short-Term Investment Options in Mutual Funds

Mutual funds offer liquid funds and ultra short term funds in the debt category, which are suitable for short investment periods. Ultra short-term funds were earlier known as liquid plus funds. Liquid funds invest in money market instruments with a maturity of 91 days or less. However, there are no such restrictions for ultra short-term funds. Who should invest in these? These are open-ended schemes. Investors with a short investment horizon or with surplus cash and low risk appetite should look at these. These could include corporate as well as retail investors. Those interested in staying invested for less than 15 days can opt for liquid funds. Retail investors who want to remain invested for two-four months, can look at ultra short-term funds. The short duration for both liquid and ultra short-term funds shields them from any interest rate volatility.   What kind of returns do they offer? In terms of an investment period less than 15 days, these funds are comparable to a ba...
Related Posts Plugin for WordPress, Blogger...
Invest in Tax Saving Mutual Funds Download Any Applications
Transact Mutual Funds Online Invest Online
Buy Gold Mutual Funds Invest Now