
Endowment or Money Back Life Insurance Policies give less returns


Since long we were targeting agents commission as a reason for Endowment, Money Back, Traditional or Traditional Child Insurance plans low returns. It is true that these policies constitute a high commission for agents. However, the real culprit is neither agents nor insurance companies, but the expense limit rules insurance companies following.

Long back, when I wrote a post on the commission earned by Life Insurance agents, then I received mixed feedback. Some were supportive and a majority were rude. Agents' fraternity fully defended the commission structure. Even though the commission is a major part of expenses in Life Insurance policies, the truth is different and that I am going to share with you all. 

Recently I got news that IRDA drafted the new guideline pertaining to the expenses of all Life and Health Insurance product (This includes Agent's commission too). This circular not yet published but sent for internal communication. This gave me a clear picture why the traditional or endowment plans unable to generate the return. Even they are failing to match the Bank FD rates. Below are some facts, which may surprise you.

Life Insurance companies follow the regulations, which formed in 1938 and 1939–

Yes, even after IRDA came into existence and the entry of private insurance companies, the expenses are still regulated by the rules of the years 1938 and 1939. These rules are called "section 17D of the Insurance Rules, 1939" and "section 40B of the Insurance Act, 1938". These old rules still followed by insurance companies for the purpose of managing expenses.

Expense depend on the age of Insurance Companies-

The cap on expenses is based on how old the insurance company. For example, it is high for new companies and low for old companies. Therefore, it is you to be a scapegoat if you bought an insurance product with the new company.

Expense depend on the product–

The cap on expenses differs for regular premium paying policies, annuity and for single premium policies. For example, the limit is set at 5% for an immediate annuity and single premium policies of an annuity. It is 10% for a deferred annuity with regular premium policies. For other products like the Endowment, Money Back or Traditional Plans the expenses are listed as below.
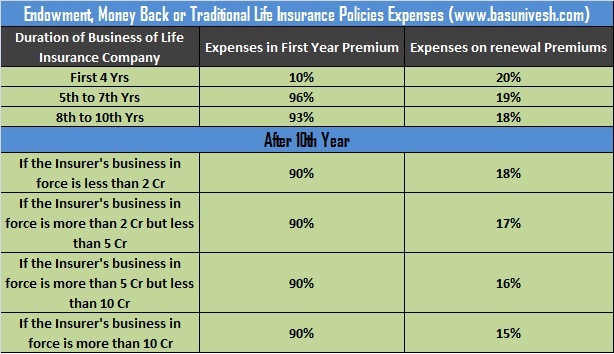
Expenses of Life Insurance Policies

You notice that only 4 years of business the expenses are minimal (in first year premium) and later on it is almost 90% of your first year premium and later on it is around 15% to 16% of premium you pay. 

Expense depend on the business in force of Insurance Company–

You notice from the above table that how the business volume of an insurance company also matters. First-year expenses are capped at 90% of premium collected. However, it decreases once the insurance company increases its volume. 

Below I explained why the traditional plans only giving you around 5% to 6%, even after investing successfully (especially LIC) in an equity markets. Let us assume that you took a traditional policy for a 15-year term and yearly you are paying Rs.100 as a premium. Then the cash flow looks like below.
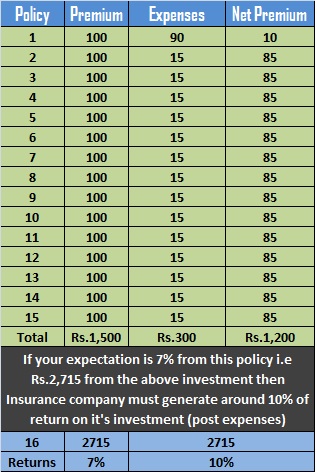
Explaination

Now being a buyer of this product, let us assume that your expectation is 7%. You assume that you invested yearly Rs.100 for 15 years and hence if we consider 7% return, then the maturity value must be around Rs.2, 715. However, for insurance companies the total invested amount during this policy is just Rs.1, 200 (excluding the expenses). Therefore, to give you the return of Rs.2, 715, the insurance company must generate around 10% return.

This is what all insurance companies providing you. They are giving you the DECENT 7% return by investing in equity or debt by smart ways  There is a huge cry whenever news items appear that LIC profited from equity investment and how much % it is actually holding in a particular company. However, for me as a buyer of Insurance+Investment product this does notmatter. What matters to me is how much life risk covered and how much I get back on my investment. They are investing wisely and there is no doubt. Why? Because generating around 10%, is a proof. However, for an end investor what matters is 7%return, not the internal return of what insurance company generated (10%).

Now it is true that Endowment or Traditional Plans are most dangerous products than the ULIPs. Hope you understood why Endowment, Money Back, or Traditional Plans generate only around 6% to 7%, even after adapting wonderful investment strategies by insurance companies

-----------------------------------------------
Invest Rs 1,50,000 and Save Tax under Section 80C. Get Great Returns by Investing in Best Performing ELSS Mutual Funds

Top 10 Tax Saving Mutual Funds to invest in India for 2016

Best 10 ELSS Mutual Funds in india for 2016

1. BNP Paribas Long Term Equity Fund

2. Axis Tax Saver Fund

3. Franklin India TaxShield

4. ICICI Prudential Long Term Equity Fund

5. IDFC Tax Advantage (ELSS) Fund

6. Birla Sun Life Tax Relief 96

7. DSP BlackRock Tax Saver Fund

8. Reliance Tax Saver (ELSS) Fund

9. Religare Tax Plan

10. Birla Sun Life Tax Plan

Invest in Best Performing 2016 Tax Saver Mutual Funds Online

Invest Online

Download Application Forms

For further information contact Prajna Capital on 94 8300 8300 by leaving a missed call

---------------------------------------------

Leave your comment with mail ID and we will answer them

OR

You can write to us at

PrajnaCapital [at] Gmail [dot] Com

OR

Leave a missed Call on 94 8300 8300

-----------------------------------------------

Popular posts from this blog

Birla SunLife FTP Series Dividend

Download Tax Saving Mutual Fund Application Forms Invest In Tax Saving Mutual Funds Online Buy Gold Mutual Funds Leave a missed Call on 94 8300 8300   Birla SunLife Mutual Fund Dividend   Birla Sun Life Mutual Fund has announced dividend under the dividend option of Birla SL FTP Series GY Reg-D , Birla SL FTP Series GY Reg-DQ , Birla SL FTP Series GY Direct-D and Birla SL FTP Series DA-D .   The quantum of dividend will be the entire distributable surplus as on the record date. The record date has been fixed as May 08, 2014. For further information contact Prajna Capital on 94 8300 8300 by leaving a missed call Leave a missed Call on 94 8300 8300 Leave your comment with mail ID and we will answer them OR You can write back to us at PrajnaCapital [at] Gmail [dot] Com ---------------...

Mutual Fund Review: Kotak Opportunities

    DESPITE a portfolio of around 57 stocks, a large-cap tilt and exposure to derivatives, debt and cash, it is not a fund for the cautious. True to its calling, it scouts for opportunities and doesn't hesitate in taking concentrated sector and stock bets. This leads to extreme returns. In the bull phase (June 15, 2006 to January 8, 2008), it delivered 91.26 per cent against the 81.29 per cent average of other opportunity funds. Unsurprisingly, it shed higher in the bear hug of 2008. While in the recent run up (March 9, 2009 to June 30, 2010) it delivered 85 per cent against its peers 87 per cent. Its charm lies in its capability to identify sector trends ahead of time. In 2005, it rode the FMCG wave and the move paid off. In the first quarter of 2006, it focused on metals. In 2007, its exposure to construction and metals that resulted in a superb performance. In 2008, it was overweight on the least-hit FMCG sector, which helped it get away with an average fall. More recently...

How to invest in the Stock Markets?

Invest In Tax Saving Mutual Funds Online Download Tax Saving Mutual Fund Application Forms Buy Gold Mutual Funds Call 0 94 8300 8300 (India)   One of the trickiest things in life is making a decision when to enter and exit the stock market. Investing in the stock markets is all about timing. Yet the timing is never right .Stocks never seem to reach the optimum price one wants .When share prices are expected to fall down to abysmal levels they rise and are soon out of one’s price range. When share prices are at low levels one keeps waiting for them to hit rock bottom and when they rise one has missed the bus. Stock markets are all about keeping one’s emotions in check. One must stand the true test of time.   What are interest rate sensitive stocks? When interest rates rise consumers who purchase expensive items such as cars on credit might postpone them. Discretionary spending is cut .Customers might postpon...

ASBA Option for Initial Public Offer (IPO)

IPO (initial public offering) applicants, particularly the unsuccessful ones, often have to face a double whammy of sorts. On the one hand they fail to get allotment of shares and on the other, they lose out on the interest during the period their money is locked —that is, if they have opted for the traditional method of issuing cheques for depositing the application money. However, if they choose the ASBA (Application Supported by Blocked Amount) facility, they can circumvent this problem. But do note that you cannot decide to make two applications – one by way of cheque payment and the other through ASBA. If you do so, it could be rejected on the grounds that it constitutes multiple applications. Introduced by Securities and Exchange Board of India ( Sebi ) in 2008, using ASBA has become mandatory for all non-retail investors. Retail investors, though, continue to have the option of choosing between the old and new mechanisms. However, it is in your interest to opt for ASBA. He...

SBI Emerging Businesses

Invest In Tax Saving Mutual Funds Online Download Tax Saving Mutual Fund Application Forms Buy Gold Mutual Funds Call 0 94 8300 8300 (India)   We like this scheme for the assumed risks it takes by investing in emerging business themes based on exports and outsourcing for which it has been handsomely rewarded.   Strategy Although the fund watches out for the opportunities in sectors based on general economic patterns, its concentrated exposure to certain sectors makes it similar to sector funds. According to the fund manager, there is no restriction on buying stocks as long as the valuation comfort exists. Since 2009, this fund has also increased its exposure to small-cap allocation that went up from an average 24.8 per cent in 2008 to an average of about 45 per cent as of now. The average market capitalisation of this fund is Rs 7,361 crore, which is on the lower band in the category. This fund restricts investm...
Related Posts Plugin for WordPress, Blogger...
Invest in Tax Saving Mutual Funds Download Any Applications
Transact Mutual Funds Online Invest Online
Buy Gold Mutual Funds Invest Now