Life Insurance Tax Corner

Download Tax Saving Mutual Fund Application Forms

Invest In Tax Saving Mutual Funds Online

Buy Gold Mutual Funds

Leave a missed Call on

94 8300 8300

Life Insurance Tax Corner

 
What are the tax benefits available to an individual in respect of premium paid on life insurance policies?
Life insurance premium paid by an individual qualifies for a deduction under Section 80C of Income Tax Act, 1961. An individual can claim deduction from gross total income on premium paid for a maximum of Rs 100,000 in each financial year. Amount deductible under Section 80C is equal to:
 
  1. 100% of the "qualifying investment", which includes life insurance premium, or
  2. Rs 100,000, whichever is lower.
Certain investments and contributions have been specified as eligible ones for Section 80C. These investments/ contributions are eligible for deduction from gross total income. And a reduction in gross total income, leads to a reduction in the tax liability. Finally, the deduction limit for Section 80C has been pegged at Rs 100,000 per annum (pa). In other words, investors can make investments/contributions of upto Rs 100,000 every year and reduce their tax liability.
 
  1. Payment of life insurance premium
  2. Contribution to employee provident fund (EPF)
  3. Repayment of principal amount on housing loan
  4. Payment of tuition fees
  5. Investments in Public Provident Fund (PPF)
  6. Investments in National Savings Certificate (NSC)
  7. Investments in tax-saving fixed deposits
  8. Investments in tax-saving mutual funds (ELSS)
  9. Investments in Infrastructure Bonds
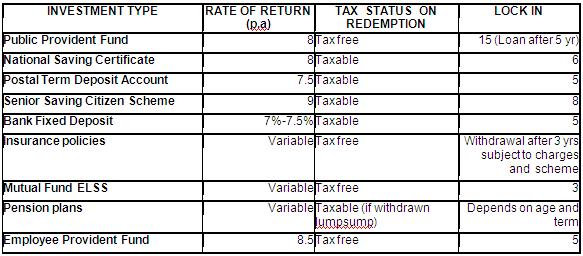
Comparison of Various Tax Saving Instruments
 
What are the tax benefits available under pension plans?

                Premium paid towards a            pension plan is eligible for a maximum benefit of Rs 100,000 under Section 80CCC. The said Section 80CCC limit falls under the overall Section 80C limit of Rs 100,000. In other words, the deduction aggregate, under Section 80C, 80CCC and 80CCD cannot exceed Rs 100,000.

Are maturity proceeds on life insurance and pension policies taxable?
The maturity proceeds of life insurance policies are not taxable. However, under pension plans, upto one-third of the maturity amount can be withdrawn in cash and the same is treated as tax-free. An annuity has to be purchased with the remaining two-third amount. Pension receipts from the same will be treated as income in the hands of the assessed and taxed accordingly.
Can tax benefits be claimed if the premium is paid by an individual on his/her spouse's policy?
Tax benefits can be claimed by an individual who pays life insurance premium on behalf of his/her spouse's policy under Section 80C of Income Tax Act, 1961.
If a person discontinues paying premium on his life insurance policy, does he get tax benefits?
If a person stops paying premium amounts on his/her life insurance policy, it amounts to discontinuation of the policy. Hence, he is not entitled to claim any tax benefits.
 
If a tax-payer discontinues the life insurance policy before premiums have been paid for a period of 2 years from the commencement of the policy, no tax deduction is allowed in respect of any premium paid on that policy in the year in which the policy is terminated.
 
Further, the amount of tax deduction, allowed for the premium paid in the preceding year, is treated as income and taxable for the year in which the policy is terminated.
If a person, investing in a Unit Linked Insurance Plan (ULIP), terminates his policy, can he claim any tax benefits on the same?
If a person participates in a Unit Linked Insurance Plan (ULIP) and then terminates his participation, he will not be entitled to claim any tax benefits.
What are the deductions available in respect of a medical insurance premium?
Medical insurance premium paid qualifies for deduction under Section 80D as follows:
  • Premium paid upto Rs 15,000 (in a financial year) is eligible for deduction from gross total income. In case of senior citizens, the limit is Rs 20,000.
  • Assesses who pay medical insurance premium for their parents can claim an additional deduction of Rs 15,000 under Section 80D. In other words, an individual who pays medical insurance premium for himself and his parents will be eligible to claim tax benefits to the extent of Rs 30,000 i.e. Rs 15,000 (for himself) and Rs 15,000 (for his parents).
  • Besides, Section 80-DD provides deduction in respect of expenditure incurred on the maintenance and medical treatment, of a dependent who is a person with severe disability. The deduction amount under this Section has been increased from Rs 75,000 to Rs 100,000.


For further information contact Prajna Capital on 94 8300 8300 by leaving a missed call

Leave a missed Call on 94 8300 8300

Leave your comment with mail ID and we will answer them

OR

You can write back to us at

PrajnaCapital [at] Gmail [dot] Com

---------------------------------------------

Invest Mutual Funds Online

Invest Any Mutual Fund Online

Download Mutual Fund Application Forms from all AMCs

Download Mutual Any Fund Application Forms

---------------------------------------------

Best Performing Mutual Funds

    1. Largecap Funds Invest Online
      1. DSP BlackRock Top 100 Fund
      2. ICICI Prudential Focused Blue Chip Fund
      3. Franklin India Bluechip
      4. ICICI Prudential Top 100 Fund

B. Large and Midcap Funds Invest Online

      1. ICICI Prudential Dynamic Plan
      2. HDFC Top 200 Fund
      3. UTI Dividend Yield Fund
      4. Birla Sun Life Front Line Equity Fund
      5. Franklin India Prima

C. Mid and SmallCap Funds Invest Online

      1. Reliance Equity Opportunities Fund
      2. DSP BlackRock Small & Midcap Fund
      3. Sundaram Select Midcap
      4. IDFC Premier Equity Fund
      5. Birla Sun Life Dividend Yield Plus
      6. SBI Emerging Businesses Fund
      7. HDFC Mid-Cap Opportunities Fund
      8. ICICI Prudential Discovery Fund

D. Small and MicroCap Funds Invest Online

      1. DSP BlackRock MicroCap Fund
      2. Franklin India Smaller Companies

E. Sector Funds Invest Online

      1. Reliance Banking Fund
      2. Reliance Banking Fund
      3. ICICI Prudential Banking and Financial Services Fund

F. Tax Saver Mutual Funds Invest Online

1. ICICI Prudential Tax Plan

2. HDFC Taxsaver

      1. DSP BlackRock Tax Saver Fund
      2. Reliance Tax Saver (ELSS) Fund

G. Gold Mutual Funds Invest Online

      1. Relaince Gold Savings Fund
      2. ICICI Prudential Regular Gold Savings Fund
      3. HDFC Gold Fund
      4. Birla Sun Life Gold

H. International funds Invest Online

1. Birla Sun Life International Equity Plan A

2. DSP BlackRock US Flexible Equity

3. FT India Feeder Franklin US Opportunities

4. ICICI Prudential US Bluechip Equity

5. Motilal Oswal MOSt Shares NASDAQ-100 ETF

Popular posts from this blog

Birla Sun Life Mutual Fund Launches Birla Sun Life NIFTY ETF

Birla Sun Life has launched a new fund namely, Birla Sun Life Nifty ETF, an open ended exchange traded fund. The new fund will be open for subscription from 4th July to 18th July 2011, at an offer price of Rs 10 per unit. The investment objective of the scheme is to generate returns that closely correspond to the total returns of securities as represented by S&P CNX Nifty, subject to tracking errors. No exit load will be charged under the scheme. The performance of the scheme will be benchmarked against S&P CNX Nifty and will be managed by Satyabrata Mohanty.   -----------------------------------------------------------------   Also, know how to buy mutual funds online:   1) DSP BlackRock Mutual Funds: http://prajnacapital.blogspot.com/2011/05/buying-dsp-blackrock-mutual-funds.html   2) Reliance Mutual Funds: http://prajnacapital.blogspot.com/2011/06/buying-reliance-mutual-funds-online.html   3) Birla Sunlife Mutual Funds: http://prajnacapital.blogspot.com/2011/...

Mutual Fund Exit Load Changes

Download Tax Saving Mutual Fund Application Forms Invest In Tax Saving Mutual Funds Online Buy Gold Mutual Funds Leave a missed Call on 94 8300 8300 Mutual Fund Exit Load Changes AMCs don't communicate about any change in exit load directly with investors, but do update on their website   The exit load applicable to your investments is the load which existed at the time when you invested in the particular fund. Any subsequent changes in the exit load will not be applicable to your investments.   However, Asset Management Companies ( AMCs ) periodically publish addendums in the newspapers, which state any change in exit loads of specific schemes managed by them. Such changes are also posted on their websites. However, a direct communication to an investor is not made, considering the costs involved in doing so. In their own interests, investors should not only track the performance of the funds they i...

Mutual Fund Reivew: Birla Sun Life Asset Allocation Conservative

Birla Sun Life Asset Allocation Conservative has numbers on its side to prove its credibility… Don't be surprised to find this Fund of Funds ( FoF ) in our recommendations. It has earned its place. And despite the difference in the structure of the product, there is no arguing with the numbers.   Of the total 6 years of its existence, the fund has been among the top 10 funds in its category in four of them. Last year it put up an average show and the only year it underperformed its peers was in 2008.   One aspect to look at when investing in an FoF is the expense ratio. The expense ratio of an FoF is capped at a lower limit of 0.75 per cent (2.50% for an actively managed fund). However, the FoF not only has its own expense (though lower) but even the expense ratio of the fund it is investing into. Fortunately, the fund manager takes that into account. "Expense is one of the important criteria used for fund selection and is the main reason for our investment in BSL Ind...

Short-Term Bond Funds

These are schemes that invest in fixed income instruments of short durations. Short-term bond funds with less than one year duration are good investment options provided you have a one-year investment horizon. Lower average maturity of the fund ensures that the fund NAV is not hit much when short-term interest rates move up. We expect the RBI to hike the policy rates by 50 to 75 basis points in this calendar year. That makes it a bit tricky for short-term bond fund investors. Check the average maturity and exit load before you invest in a short-term bond fund. As a rule of thumb, the average maturity should be less than your investment time frame. Some funds do charge an exit load if you log out early. To avoid such a cut in the returns earned, it is better to check at what threshold of time the fund charges an exit load. The funds have a wide range of 'exit load' thresholds. Some charge an exit load if you were to redeem units within 90 days, while there are some that let ...

Short-Term Investment Options in Mutual Funds

Mutual funds offer liquid funds and ultra short term funds in the debt category, which are suitable for short investment periods. Ultra short-term funds were earlier known as liquid plus funds. Liquid funds invest in money market instruments with a maturity of 91 days or less. However, there are no such restrictions for ultra short-term funds. Who should invest in these? These are open-ended schemes. Investors with a short investment horizon or with surplus cash and low risk appetite should look at these. These could include corporate as well as retail investors. Those interested in staying invested for less than 15 days can opt for liquid funds. Retail investors who want to remain invested for two-four months, can look at ultra short-term funds. The short duration for both liquid and ultra short-term funds shields them from any interest rate volatility.   What kind of returns do they offer? In terms of an investment period less than 15 days, these funds are comparable to a ba...
Related Posts Plugin for WordPress, Blogger...
Invest in Tax Saving Mutual Funds Download Any Applications
Transact Mutual Funds Online Invest Online
Buy Gold Mutual Funds Invest Now