
Single Premium ULIP plans vs Regular Premium ULIP plans

Individuals who are disciplined for regular investing and looking for a good long term investment option backed with life cover and do not mind the 5-year lock in period should be investing in regular premium ULIPs.

There has been a recent spike in the sale of single premium ULIP plans as compared to regular premiums. In the single premium plan, an insurer gets coverage for full term by paying premium amount in a lumpsum. Whereas, in regular premium ULIP plan, an insurer needs to pay premiums in intervals such as monthly, quarterly, half-yearly or annually for the policy.

The private sector insurers registered a hike in the growth of 54.75% in the single premium segment in April-June 2018 at the same time the regular premium grew just 3.84% during the same period.

Investors have taken into account the Long Term Capital Gains (LTCG) tax on equity mutual funds, post the announcement in the Union Budget and hence there was an overall growth in ULIP sales. New plans have lower charges and are more transparent so it's gaining investors' confidence. Let's understand key differences between single premium and regular premium ULIP plans for investors to take informed decisions before opting for one.

Why investors are opting for single premium ULIP plans?

While buying a single premium ULIP plan, a buyer of the policy needs to have a lumpsum amount to invest in existing or new schemes getting launched.  Lumpsum investors have always been a key chunk of the market. This is mainly because a good proportion of the customers have a good amount of investible surplus right now, but they shy away from the commitment of recurring investments in regular premium ULIP plans.

We see a spike in sales as many companies are launching single premium insurance plans where product offering and pricing is better than the existing plans."

Who should be investing in single premium or regular premium ULIP plans?

Single premium ULIPs should be bought by individuals who can afford its expensive premium. Even individual with uneven cash flows can invest in such a mode as their future premiums might be uncertain.

Investors who have unexpected windfall gains like bonuses, profits, huge income from property sale, etc. also investing their gains in these single premium plans.

Lastly, individuals who want to avoid the hassle of regular payment of premium should be investing in the single premium plan.

Individuals who are disciplined enough for regular investing and looking for a good long term investment option backed with life cover and who do not mind the lock in period of 5 years should be investing in regular premium ULIPs

The positives and drawbacks of single and regular premium ULIP plans

Table 1_ULIP story

Illustration of fund value comparison in single premium vs regular premium ULIP plans
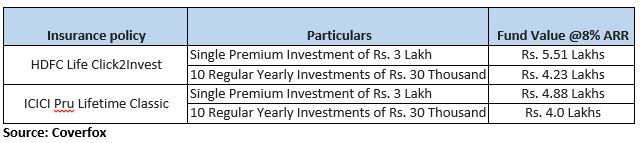
In ULIP products, the premiums remain same since you choose how much you want to invest. It is the output, the maturity amount that differs, basis the cost of the product, which is a net of all the charges it deducts and the additional allocations it gives. Also, you cannot simply compare the maturity fund values for regular and single premium, since the former has repeated investment inflow, while the latter just grows on the initial investment amount.
Table 2_ULIP story

Tax benefits

In single premium ULIP plans, if the premium paid in a year is more than 10% of the sum assured of the plan, then the total premium is not eligible for tax exemption.

Example:

If the annual premium of a plan is Rs 35,000 and cover amount is Rs 1,75,000, therefore, only Rs 17,500 which is 10% of sum assured (Rs 35,000) will be tax-free and not the entire amount of Rs 35,000 will be exempted from tax.

Be careful while investing in single premium investment plans and check if the annual premium is less than 10% of the sum assured as this criteria is very often not met in such plans. The premiums are not fully tax exempted under Section 80C, also the maturity amount is also fully taxable.

On the other hand, regular premium ULIP policy will provide you tax deduction benefit continuously i.e. over the tenure of the policy under section 80C.

You can also avail tax benefits of up to Rs 1.5 lakh over a period of 15 years (tenure of the policy).

Hence, a single premium ULIP plan can be a shortcoming when compared with the regular premium ULIP plan.

Regular premium ULIP plans are value for money in uncertain demise of policy holder

When it comes to value for money, regular premium ULIP plans are more value for money. Suppose the policyholder meets an untimely death prior to the end of the policy term, the nominee need not pay the pending premiums once the sum assured is received. While in case of single premiums wherein you pay the entire premium in one go, if the policyholder dies during the term they would have unnecessarily paid for the future premiums


SIPs are Best Investments as Stock Market s are move up and down. Volatile is your best friend in making Money and creating enormous Wealth, If you have patience and long term Investing orientation. Invest in Best SIP Mutual Funds and get good returns over a period of time. Know which are the Top SIP Funds to Invest Save Tax Get Rich - Best ELSS Funds

For more information on Top SIP Mutual Funds contact Save Tax Get Rich on 94 8300 8300

OR

You can write to us at

Invest [at] SaveTaxGetRich [dot] Com

Popular posts from this blog

Mutual Fund Review: Kotak Opportunities

    DESPITE a portfolio of around 57 stocks, a large-cap tilt and exposure to derivatives, debt and cash, it is not a fund for the cautious. True to its calling, it scouts for opportunities and doesn't hesitate in taking concentrated sector and stock bets. This leads to extreme returns. In the bull phase (June 15, 2006 to January 8, 2008), it delivered 91.26 per cent against the 81.29 per cent average of other opportunity funds. Unsurprisingly, it shed higher in the bear hug of 2008. While in the recent run up (March 9, 2009 to June 30, 2010) it delivered 85 per cent against its peers 87 per cent. Its charm lies in its capability to identify sector trends ahead of time. In 2005, it rode the FMCG wave and the move paid off. In the first quarter of 2006, it focused on metals. In 2007, its exposure to construction and metals that resulted in a superb performance. In 2008, it was overweight on the least-hit FMCG sector, which helped it get away with an average fall. More recently...

How to invest in the Stock Markets?

Invest In Tax Saving Mutual Funds Online Download Tax Saving Mutual Fund Application Forms Buy Gold Mutual Funds Call 0 94 8300 8300 (India)   One of the trickiest things in life is making a decision when to enter and exit the stock market. Investing in the stock markets is all about timing. Yet the timing is never right .Stocks never seem to reach the optimum price one wants .When share prices are expected to fall down to abysmal levels they rise and are soon out of one’s price range. When share prices are at low levels one keeps waiting for them to hit rock bottom and when they rise one has missed the bus. Stock markets are all about keeping one’s emotions in check. One must stand the true test of time.   What are interest rate sensitive stocks? When interest rates rise consumers who purchase expensive items such as cars on credit might postpone them. Discretionary spending is cut .Customers might postpon...

ASBA Option for Initial Public Offer (IPO)

IPO (initial public offering) applicants, particularly the unsuccessful ones, often have to face a double whammy of sorts. On the one hand they fail to get allotment of shares and on the other, they lose out on the interest during the period their money is locked —that is, if they have opted for the traditional method of issuing cheques for depositing the application money. However, if they choose the ASBA (Application Supported by Blocked Amount) facility, they can circumvent this problem. But do note that you cannot decide to make two applications – one by way of cheque payment and the other through ASBA. If you do so, it could be rejected on the grounds that it constitutes multiple applications. Introduced by Securities and Exchange Board of India ( Sebi ) in 2008, using ASBA has become mandatory for all non-retail investors. Retail investors, though, continue to have the option of choosing between the old and new mechanisms. However, it is in your interest to opt for ASBA. He...

Tata Growth Renamed as Tata Mid Cap Growth

Tata Mutual Fund has announced a change in the name of Tata Growth to Tata Mid Cap Growth with effect from November 22, 2012.   As per the investment strategy, the scheme invests a minimum of 65% in equity and equity related securities of well researched companies of the midcap segment. Some of the best Tax Saving Mutual Funds available ( ELSS Mutual Funds ) ICICI Prudential Tax Plan Invest Online HDFC TaxSaver Invest Online DSP BlackRock Tax Saver Fund Invest Online Reliance Tax Saver (ELSS) Fund Invest Online Birla Sun Life Tax Relief '96 Invest Online IDFC Tax Advantage (ELSS) Fund Invest Online SBI Magnum Tax Gain Scheme 1993 Invest Online Sundaram Tax Saver Invest Online Edelweiss ELSS Invest Online ---------------------------------------- Happy Investing!! We can help. Call 0 94 8300 8300 (India) Leave your comment wit...

Know your PAN

    What is a PAN? PAN, or Permanent Account Number is a unique 10 digit alphanumeric that is given to each taxpayer by the Income Tax Department. It is a mandatory requirement for all financial transactions such as receiving salary, investing in mutual funds and also purchasing assets above a certain specified limit. The number helps track financial transactions and thereby prevent tax evasion. Explaining the 10 digits… The first 5 characters of the PAN are letters and the next 4 numbers, and the last one is an alphabet. The meaning of each number has been explained further. First three characters are alphabetic series running from AAA to ZZZ as issued by IT Department. Fourth character of PAN represents the status of the PAN holder. C — Company P — Person H — HUF (Hindu Undivided Family) F — Firm A — Association of Persons (AOP) T — Trust B — Body of Individuals (BOI) L — Local Authority J — Artificial Juridical Person G — Government Fifth character represents first character of t...
Related Posts Plugin for WordPress, Blogger...
Invest in Tax Saving Mutual Funds Download Any Applications
Transact Mutual Funds Online Invest Online
Buy Gold Mutual Funds Invest Now